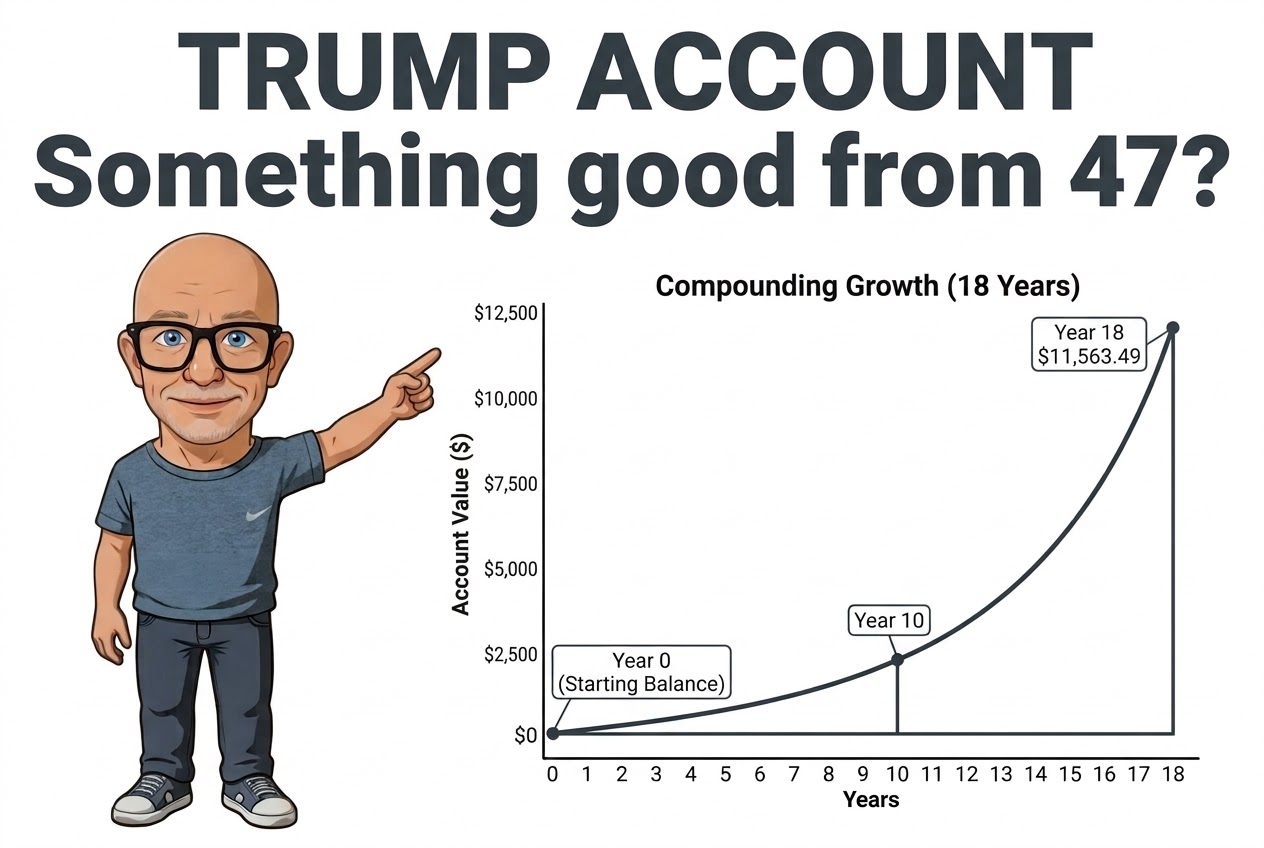
The Trump Account - Something Good from DJT?
Codger’s Corner: When a Politician You Dislike Launches a Policy Worth Supporting
By Ned T. Smith, The Crypto Codger
In both politics and investing, holding two competing thoughts in your head at the same time is an essential survival skill. As an experienced investor who has watched administrations come and go for four decades, I have never been a fan of Donald Trump as President. In fact, I disagree with roughly 95% of his actions, rhetoric, and economic policies.
Yet part of being a pragmatic, experienced market observer is giving credit where credit is due. When a policy falls into that remaining 5% and genuinely helps everyday American families build long-term wealth, I am going to support it regardless of whose name is stamped on the wrapper. That brings us to the newly created Trump Accounts for newborns in the United States.
What Are Trump Accounts and Why Do They Matter?
Created under federal legislation and launched in July 2026, Trump Accounts function as starter IRAs (Individual Retirement Accounts) for children. For every eligible American child born between January 1, 2025, and December 31, 2028, the United States Treasury deposits $1,000 in initial seed money into an account owned by the child and managed by a parent or legal guardian. Families and employers can also contribute up to $5,000 per year until the child turns 18.
Why do I support this program? Because it introduces millions of young families to the single most powerful force in finance: compounding returns over time. Think of compounding like rolling a snowball down a long, snowy mountain. At the top of the ridge, the snowball is small enough to hold in your hands. As it rolls uninterrupted down the slope for 18 years, each turn packs on a thicker layer of snow until it builds unstoppable momentum on its own. Locking that $1,000 away until age 18 teaches patience and long-term discipline.
However, there is one major flaw in how these accounts are structured today. Under current rules, the money must be invested exclusively in traditional stock index funds, such as those tracking the S&P 500 (Standard and Poor's 500)—a basket of the 500 largest publicly traded companies in the United States. Right now, parents are not allowed to allocate even a modest slice of a Trump Account into Bitcoin or regulated spot Bitcoin ETFs (Exchange-Traded Funds).
Traditional Stocks Versus a Modern 75/25 Split
To see why leaving digital commodities out of a newborn’s 18-year time horizon is a costly oversight, let us run the numbers on that initial $1,000 federal deposit with zero additional family contributions over 18 years:
Bitcoin Allocation (20% Expected Compounded Annual Return): $250 (25% of the starting $1,000 balance) is invested in Bitcoin within the blended portfolio.
S&P 500 Allocation (11% Expected Compounded Annual Return): $1,000 (100% of the starting balance) is invested in the S&P 500 in the standard Trump Account, compared against $750 (75% of the starting balance) in the blended portfolio.
Child's Age | 100% S&P 500 (11%) | 75% S&P 500 ($750) | 25% Bitcoin ($250) | 75/25 Combined Total |
Birth (Start) | $1,000.00 | $750.00 | $250.00 | $1,000.00 |
Year 1 | $1,110.00 | $832.50 | $300.00 | $1,132.50 |
Year 2 | $1,232.10 | $924.08 | $360.00 | $1,284.08 |
Year 3 | $1,367.63 | $1,025.72 | $432.00 | $1,457.72 |
Year 4 | $1,518.07 | $1,138.55 | $518.40 | $1,656.95 |
Year 5 | $1,685.06 | $1,263.79 | $622.08 | $1,885.87 |
Year 6 | $1,870.41 | $1,402.81 | $746.50 | $2,149.31 |
Year 7 | $2,076.16 | $1,557.12 | $895.80 | $2,452.92 |
Year 8 | $2,304.54 | $1,728.40 | $1,074.95 | $2,803.35 |
Year 9 | $2,558.04 | $1,918.53 | $1,289.95 | $3,208.48 |
Year 10 | $2,839.42 | $2,129.57 | $1,547.93 | $3,677.50 |
Year 11 | $3,151.76 | $2,363.82 | $1,857.52 | $4,221.34 |
Year 12 | $3,498.45 | $2,623.84 | $2,229.03 | $4,852.87 |
Year 13 | $3,883.28 | $2,912.46 | $2,674.83 | $5,587.29 |
Year 14 | $4,310.44 | $3,232.83 | $3,209.80 | $6,442.63 |
Year 15 | $4,784.59 | $3,588.44 | $3,851.76 | $7,440.20 |
Year 16 | $5,310.89 | $3,983.17 | $4,622.11 | $8,605.28 |
Year 17 | $5,895.09 | $4,421.32 | $5,546.53 | $9,967.85 |
Year 18 | $6,543.55 | $4,907.66 | $6,655.83 | $11,563.49 |
What the 18-Year Numbers Tell Us
Look closely at the Year 18 row in the table above. By the time that newborn turns 18, the $250 Bitcoin slice alone grows to $6,655.83—which by itself beats the entire $6,543.55 total of the 100% S&P 500 account.
When you combine that $6,655.83 in Bitcoin with the $4,907.66 generated by the 75% S&P 500 slice, the blended account reaches $11,563.49. Here is how the final 18-year results rank by percentage gain from highest to lowest:
25% Bitcoin Slice ($250 to $6,655.83): 2,562.3% total return, generating 57.6% of the blended account's final dollar value from just 25% of the starting money.
Combined 75/25 Account ($1,000 to $11,563.49): 1,056.3% total return, delivering $5,019.94 more (76.7% higher total wealth) than the all-stock account.
100% S&P 500 Account ($1,000 to $6,543.55): 554.4% total return, providing a solid baseline foundation but leaving substantial long-term growth on the table.
How Parents and Grandparents Can Act Today
While these projections are educational illustrations rather than guaranteed returns or personalized investment advice, they highlight a clear game plan for families welcoming a new child or grandchild:
Claim the Free $1,000 Seed Money: Open a Trump Account for any child born between 2025 and 2028 as soon as their Social Security number is issued so you never leave free capital on the table.
Build Your Own 25% Digital Asset Sleeve: Until Washington updates the rules to allow regulated digital commodities inside Trump Accounts, parents and grandparents can set aside $250 of family gift money in a separate custodial account dedicated to Bitcoin or a spot Bitcoin ETF to achieve that 75/25 balance on their own.
Get Educated on Digital Assets: To learn how to safely add digital commodities to your family's long-term financial strategy in plain English, pick up a copy of my book, "Crypto = Digital Assets," available now on Amazon Kindle, and visit thecryptocodger.com.
For more great ideas and concepts on how to implement Digital Assets in your long term strategies contact the Codger and setup a time to chat!
